ASML Excel edition
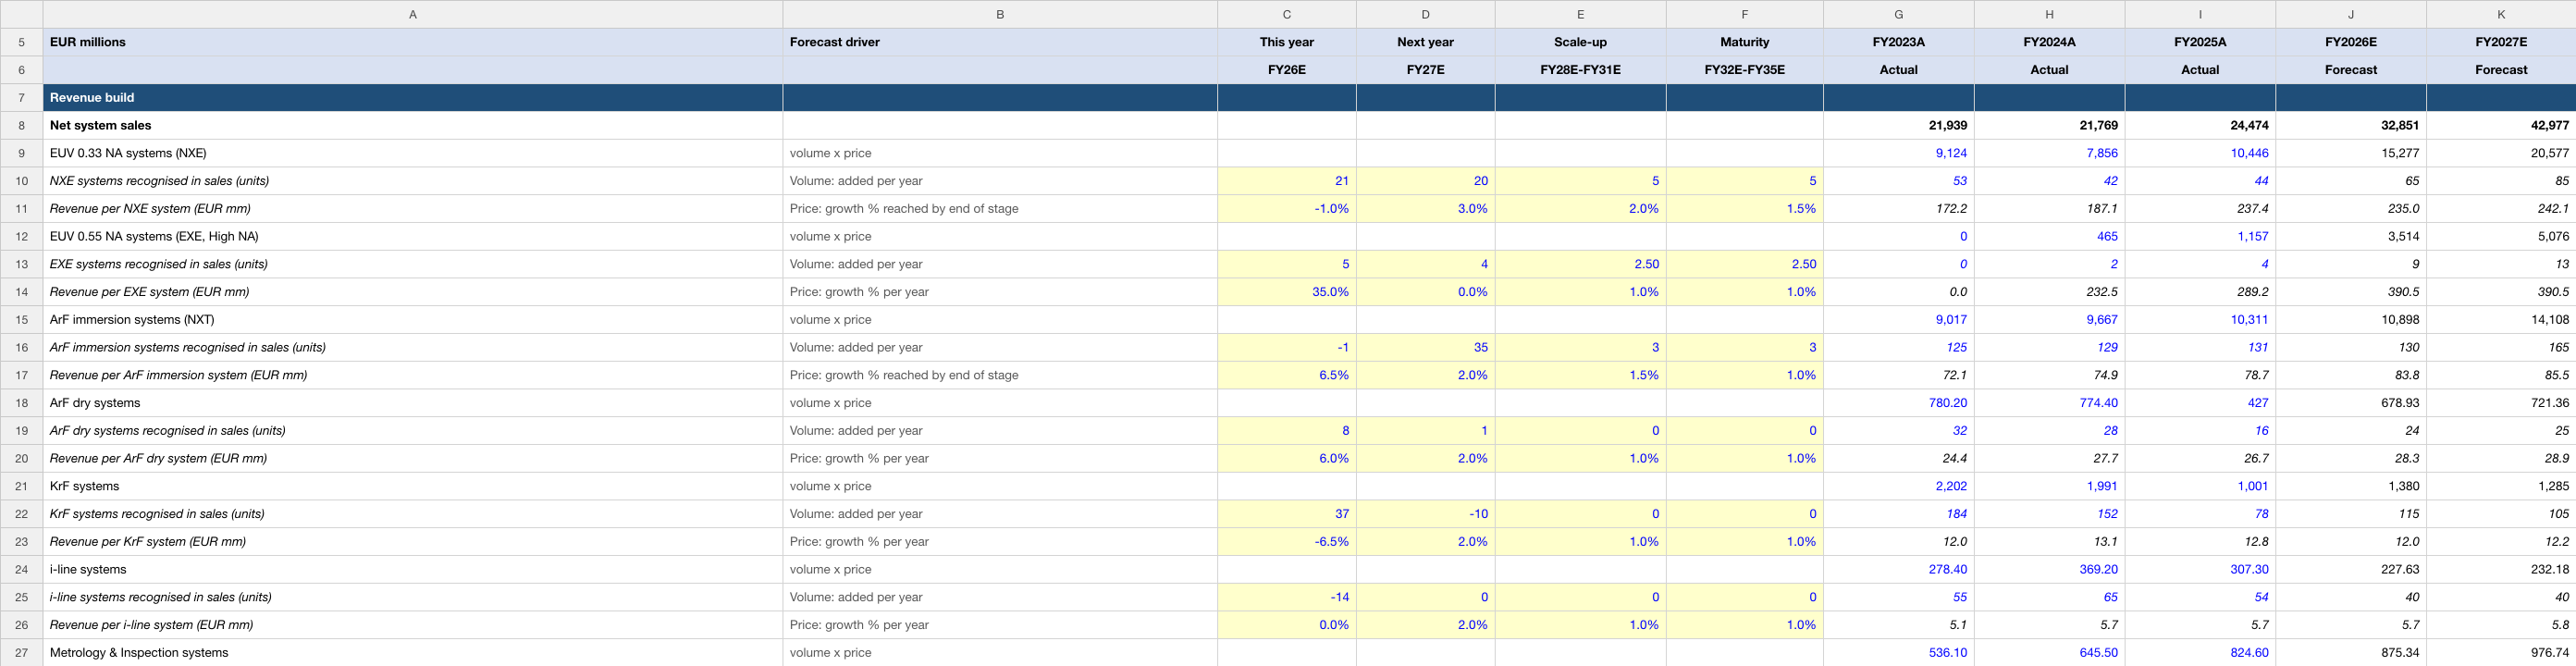
EUV, ArF immersion and dry system units, revenue per system, plus Installed Base Management. Change the highlighted assumptions to explore the relationship between operating performance, cash flow and value.
Inside the workbook
- Income Statement, Balance Sheet, Cash Flow and DCF Valuation worksheets.
- Three historical fiscal years and ten modeled periods with source and forecast notes.
- Discounted cash flows, terminal-value methods and valuation sensitivities.
| Edition detail | Included |
|---|---|
| Valuation date | 5 October 2026 |
| Historical periods | FY2023A, FY2024A, FY2025A |
| Modeled periods | FY2026E–FY2035E |
| Financial currency | EUR in millions |
| Format | Editable .xlsx · Four worksheets · 53.5 KB |
| Price | US$19.99 for 12 months of company-model access |
Historical figures recorded in this edition
These are cached historical entries in the uploaded ASML workbook, dated 5 October 2026. Fiscal-year labels and units follow the file; they are not live data. The source annotations below are the model author’s references, rather than an independent audit of every figure.
| Metric | FY2023A | FY2024A | FY2025A |
|---|---|---|---|
| Total revenue | 27,558.50 | 28,262.90 | 32,667.30 |
| Operating income (EBIT) | 9,042.30 | 9,022.60 | 11,301.40 |
| Net income | 7,839.00 | 7,571.60 | 9,609.40 |
How this edition builds the forecast
EUV, ArF immersion and dry system units, revenue per system, plus Installed Base Management. The first forecast period is FY2026E. The editable assumptions distinguish the operating driver from the reasoning used to forecast it.
NXE systems recognised in sales (units)
Mechanism: Volume: added per year
Inputs shown in this file: FY26E: 21 · FY27E: 20 · FY28E-FY31E: 5 · FY32E-FY35E: 5
Read this driver’s forecast rationale
NXE systems recognised were 53 / 42 / 44 in FY23-FY25; 1H26 was 29 vs 24 in 1H25 (SEC Form 6-K filed 2026-07-15 (Statutory Interim Report for the six months ended 2026-06-28, Ex. 99.4), net system sales by technology). On 2026-07-15 the company said 2026 low NA EUV capacity is around 65, that it plans to add 30% to that for 2027 (about 85) and is investigating another 30% for 2028, and that order intake remained extremely strong (SEC Form 6-K filed 2026-07-15 (Q2 2026 results press release, Ex. 99.1), CEO statement); year-end 2025 backlog was EUR 38.8bn (SEC Form 6-K filed 2026-01-28 (Q4 2025 results press release, Ex. 99.1, and presentation)). Assumption: 65 recognised in FY26 (full use of the stated capacity) and about 85 in FY27 (also what puts revenue near consensus), then +5 a year from FY28 to FY35, well below the +30% for 2028 that is only being investigated. That is 40 systems over FY28-FY35, the total a taper from about +7 to about +3 a year would also add, but spread evenly because two different levels would make unit growth drop at the FY32 stage boundary.
Read the workbook’s historical source annotation
SEC Form 20-F for the year ended 2025-12-31 (Annual Report 2025), filed 2026-02-25, Note 3 - Revenue, net system sales per technology, units recognised, p. 288; SEC Form 20-F for the year ended 2025-12-31 (Annual Report 2025), filed 2026-02-25, Financial performance KPIs, p. 56 (44 NXE in 2025, 42 in 2024)
Revenue per NXE system (EUR mm)
Mechanism: Price: growth % reached by end of stage
Inputs shown in this file: FY26E: -1.0% · FY27E: 3.0% · FY28E-FY31E: 2.0% · FY32E-FY35E: 1.5%
Read this driver’s forecast rationale
Revenue per NXE system was EUR 172mm / 187mm / 237mm in FY23-FY25 as the NXE:3800E ramped, and EUR 231mm in 1H26 (6,708.5 / 29 systems; SEC Form 6-K filed 2026-07-15 (Statutory Interim Report for the six months ended 2026-06-28, Ex. 99.4)). Assumption: about EUR 235mm in FY26 (slightly below FY25, in line with the 1H26 figure), +3% in FY27 on NXE:3800E / 3800F / 4200G mix and price terms, then growth fading year by year to +2% by FY31 and +1.5% by FY35 (roughly inflation).
EXE systems recognised in sales (units)
Mechanism: Volume: added per year
Inputs shown in this file: FY26E: 5 · FY27E: 4 · FY28E-FY31E: 2.5 · FY32E-FY35E: 2.5
Read this driver’s forecast rationale
EXE systems recognised were 0 / 2 / 4 in FY23-FY25 and 3 in 1H26 (EUR 1,188.9mm; SEC Form 6-K filed 2026-07-15 (Statutory Interim Report for the six months ended 2026-06-28, Ex. 99.4)). Two High NA systems were recognised in Q4 2025 (SEC Form 6-K filed 2026-01-28 (Q4 2025 results press release, Ex. 99.1, and presentation)), and the first high-volume logic process qualified on High NA in Q2 2026 (SEC Form 6-K filed 2026-07-15 (Q2 2026 results presentation, Ex. 99.2)). The company gives no EXE capacity, so this is the least certain revenue driver and is the one set so that FY26 total revenue lands on the guidance mid-point (EUR 44bn). Assumption: 9 recognised in FY26 (3 already in 1H26), 13 in FY27, then +2.5 a year (five systems every two years) from FY28 to FY35 as DRAM and leading-edge logic customers adopt High NA. That is 20 systems over FY28-FY35, the total a taper from about +3 to about +2 a year would also add, but spread evenly because two different levels would make unit growth drop at the FY32 stage boundary.
Read the workbook’s historical source annotation
SEC Form 20-F for the year ended 2025-12-31 (Annual Report 2025), filed 2026-02-25, Note 3 - Revenue, net system sales per technology, units recognised, p. 288; SEC Form 20-F for the year ended 2025-12-31 (Annual Report 2025), filed 2026-02-25, Financial performance KPIs, p. 56 (two EXE in 2024, four in 2025)
The later forecast years contain modeling judgments. The historical labels, financial-period dates and valuation date are separate from any stock-price observation; this page does not supply a current market quote.
One company. One year of access.
Your US$19.99 one-time purchase includes 12 months of downloads and updates for this company’s model. No automatic renewal. Downloaded files remain usable after access ends; no fixed update cadence is promised.
Read the current version’s notes
EUR in millions, fiscal year ending December 31. Base case in euros (US GAAP, as filed). FY2026E revenue is set to the company's own full-year guidance (EUR 43-45bn, mid-point) with six months already reported; FY2027E lands on analyst consensus; later years are this model's own assumptions, each explained in the last column.
Dates and descriptions reflect this workbook’s notes. They are not a claim of independent audit or a guarantee that its forecasts will occur.